Planning a Manufactured Home Purchase in Statesville, North Carolina
Key Takeaways
- Buying a manufactured home in Statesville involves more than the home’s listed price; buyers should account for land, financing, utilities, permits, delivery, installation, and site work.
- Review the property before choosing a home to confirm zoning, access, drainage, utility availability, and other site requirements.
- Build separate upfront and monthly budgets to understand the full cost of purchasing and owning the home.
- Compare floor plans based on household needs, storage, accessibility, layout, and long-term use rather than size alone.
- Review loan terms carefully, including the APR, repayment period, fees, down payment, and total amount repaid.
- Confirm which delivery, setup, foundation, utility, permit, and installation responsibilities are included in the purchase agreement.
- Keep important documents, warranties, specifications, permits, and inspection records organized throughout the buying process.
- Allow flexibility in the timeline because permitting, weather, site conditions, financing, utilities, and delivery access can affect the move-in date.
Buying a home in the Statesville area involves more than selecting a floor plan and comparing advertised prices. People exploring manufactured homes for sale should approach the process as a complete housing project, including financing, land, access, utilities, permits, setup, and long-term ownership costs. For more information on available options in the area, visit 1stchoicestatesville.com. Whether a household plans to place a home on family land, purchase a rural parcel in Iredell County, or move into a land-lease community, early planning can reduce surprises. The best option is not necessarily the largest home or the lowest listed price. It is the home that fits the site, budget, daily needs, and plans.
Why Careful Planning Matters in Statesville
Statesville buyers may encounter a wide range of property conditions, from established neighborhoods with existing utility connections to rural sites that need driveway work, grading, a well, or a septic system. Those differences can substantially change both the upfront cost and the time needed before move-in. A lower home price does not automatically produce a lower monthly cost. A loan with a longer repayment period, higher fees, required insurance, land payments, or ongoing lot rent can change the household budget. Buyers should compare total costs rather than relying on one number from an initial quote. People also use the term mobile homes when researching factory-built housing, but buyers should confirm the home type, age, condition, construction standards, and financing classification before signing an agreement. These details may affect placement, lending, insurance, and future resale considerations.
Build a Full Purchase Budget
Create two separate budgets: one for the project before move-in and another for monthly ownership. This approach makes it easier to see whether the home remains affordable after accounting for all required steps.
Upfront Costs to List
- Home price, down payment, loan fees, and closing costs
- Land purchase costs or initial land-lease expenses
- Transportation, delivery, installation, anchoring, and foundation work
- Grading, drainage, driveway improvements, and tree clearing
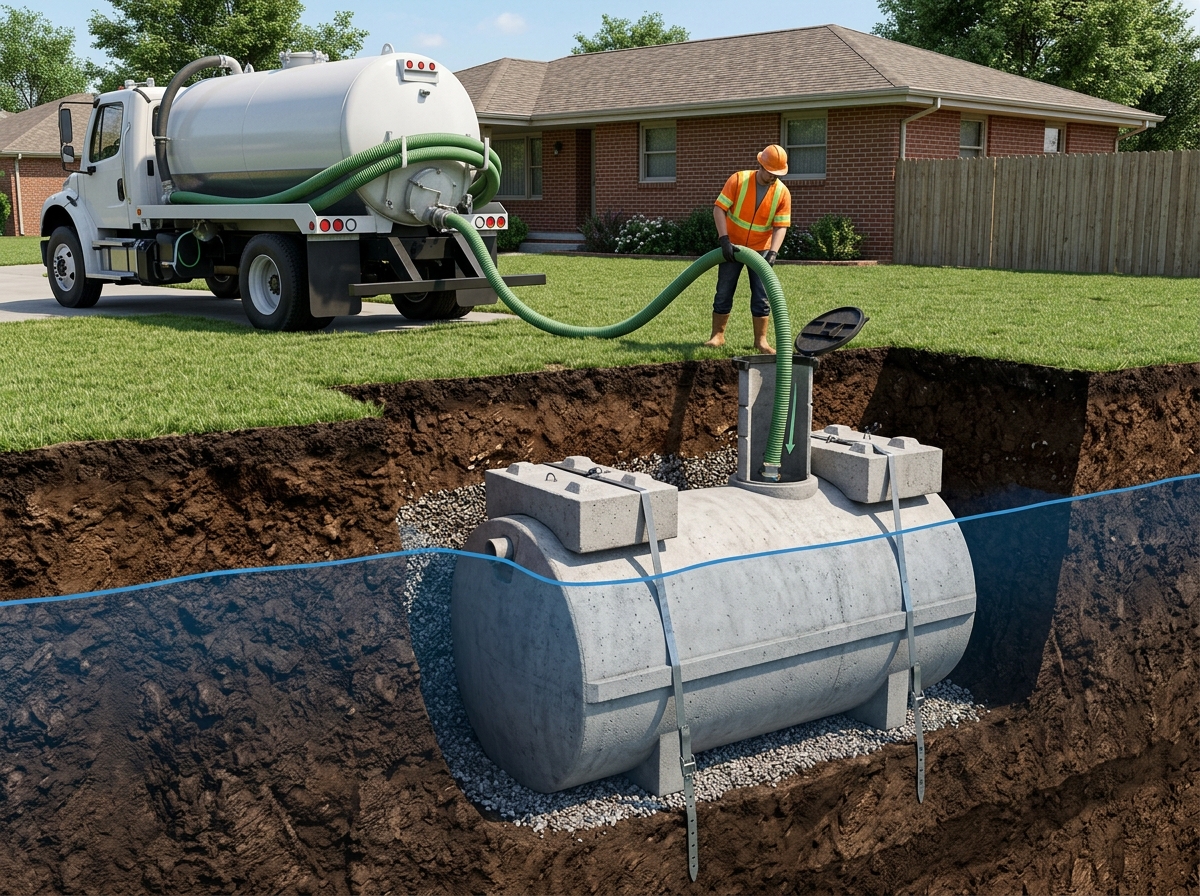
- Water, sewer, electric, gas, septic, or well-related work
- Permits, inspections, steps, porches, skirting, and moving expenses
For example, a buyer can start with the home price, then add every known site and closing expense. Any item without a written estimate should be marked as a possible contingency rather than assumed to be free or included.
Check the Land Before Choosing a Home
Land should be reviewed before a buyer becomes committed to a particular model. Confirm with the appropriate local offices whether manufactured housing is permitted, whether there are dimensional or appearance requirements, and which permits are needed for the intended site. Also evaluate practical conditions. Can delivery equipment reach the property? Is there a safe route around trees, overhead lines, tight turns, or soft ground? Does water drain away from the proposed foundation area? Is public water and sewer available, or will the site require private systems? These questions are often easier and less expensive to answer before a contract is finalized.
Compare Home Types and Floor Plans
Compare layouts according to how the household actually lives. A larger home can add useful space, but a well-designed smaller plan may offer better storage, traffic flow, and operating costs.
- Count bedrooms and bathrooms based on current and expected household needs.
- Check closet space, pantry storage, linen storage, and outdoor storage needs.
- Consider laundry placement, kitchen workflow, natural light, and window locations.
- Think about accessibility features, including entry steps, hallway width, and primary-bedroom location.
- Ask which features are standard, optional, or excluded from the quoted price.
Review Financing Options
Financing can differ depending on whether the buyer owns the land, how the home is titled, the foundation plan, credit history, and the loan amount. Buyers should compare more than the estimated payment. Review the annual percentage rate, repayment term, lender fees, down payment, and total amount repaid over the life of the loan. A preapproval can help establish a realistic price range, but buyers should still read the loan estimate provided by a lender carefully before closing. This form is designed to show key costs and terms, making it useful for comparing offers from multiple lenders.
Plan Delivery, Setup, and Utilities
Even when a home is ready for delivery, the site may not be. A practical sequence is to confirm the delivery route, clear obstacles, prepare the driveway and pad, complete drainage work, arrange utilities, and schedule installation and inspections. Buyers should request a written breakdown showing which setup services are included, who coordinates permits, and who is responsible for unexpected site conditions. Federal homeowner guidance notes that site access, soil conditions, foundation systems, anchoring, utility connections, and local permits are all important installation considerations. Resources for manufactured housing homeowners can help buyers understand the documents and installation information they should receive.
Review Documents and Quality Details
Keep copies of the purchase agreement, itemized pricing sheet, floor plan, specifications, warranty information, installation plan, permit records, and inspection results. Review every verbal promise and ensure important commitments are in writing. For newer manufactured homes, buyers can also ask about the HUD certification label and the home’s data plate. These records identify construction-related information, including the conditions for which the home was designed. An independent inspection may also provide another opportunity to identify concerns before final acceptance.
Create a Realistic Timeline
- Set a target monthly budget, check credit, and identify household priorities.
- Review land access, zoning, utilities, drainage, and site-work needs.
- Compare homes, features, financing offers, and written estimates.
- Finalize permits, financing, site plans, and contract details.
- Complete site preparation, delivery, installation, inspections, and utility connections.
Timelines can change because of weather, lender requirements, utility scheduling, permitting, site conditions, and delivery access. Keeping some flexibility in moving arrangements is often wiser than relying on a single fixed date.
Pre-Purchase Checklist
- □ The monthly payment fits the household budget.
- □ Total project costs are listed in writing.
- □ Placement rules and permits have been confirmed.
- □ Delivery access and site conditions have been reviewed.
- □ Utility and site-work costs have been estimated.
- □ Financing terms have been compared.
- □ Warranty terms and installation responsibilities are understood.
- □ A cash reserve remains after closing and move-in expenses.
Conclusion
A successful manufactured home purchase in Statesville begins with preparation, not just shopping. By verifying the land, building a complete budget, comparing loan terms, documenting responsibilities, and allowing time for site work, buyers can make decisions with greater confidence and reduce avoidable delays on the path to move-in. It is also important to account for permits, utility connections, foundation requirements, transportation, installation, and other costs that may not be included in the home’s advertised price. Buyers should understand what the seller, manufacturer, contractor, and lender are responsible for before signing agreements. Taking time to review these details can make the process more organized and help buyers prepare for unexpected expenses or scheduling changes. With careful planning from the property search through installation, buyers can create a clearer path toward a manufactured home that fits their needs and budget.
Alex

Hi, I am Alex ; I am an entrepreneur, father, mentor, and adventurer passionate about life. At this moment, I am writing about business and lifestyle ideas.



Post Comment